Author: LBank Research Analyst: Ludo
Disclaimer: This report is compiled and analyzed from publicly available information and is intended solely for information sharing and research discussion. It does not constitute investment advice, a securities recommendation, a trading instruction, or any guarantee of returns. The company operations, valuations, market prices, and consensus expectations discussed herein may change over time. Readers should independently verify the data and make their own decisions.
1. Core Conclusion
Overall assessment: Oura Inc. is a strong consumer health franchise, but its proposed IPO valuation already anticipates a substantial transition from hardware growth to recurring profitability. At the USD 42 indicative midpoint, approximately 9.5x trailing revenue leaves the fundamental risk-reward tilted cautious. The decisive variable is operating profit generated per retained paying member after acquisition, product support and development costs.
-
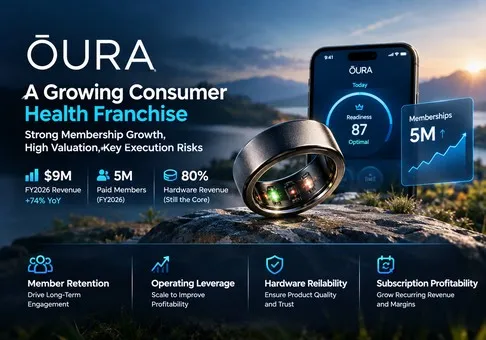
Demand is established and the ring has a distinct use case. Revenue reached USD 1,214.506 million in the nine months ended June 30, 2026, up 74.1%, while Paid Members doubled to 5.0 million. A comfortable device worn during sleep can build a daily relationship with customers. This gives Oura a credible route to repeat revenue, although the member count alone does not establish pricing power.
-
Membership is the economic opportunity, with hardware still carrying the business. Subscriptions contributed USD 240.526 million, or 19.8% of revenue, and a company-disclosed 89% gross margin. Hardware contributed 80.2%. Treating the entire company as mature subscription software would apply the economics of a minority revenue stream to the whole enterprise.
-
Operating leverage is weaker than headline net income suggests. GAAP operating margin fell from 8.6% to 5.9% across comparable nine-month periods. Revenue increased USD 516.937 million, but operating profit increased only USD 10.923 million: a 2.1% incremental operating margin. The June quarter also recorded a USD 9.966 million net loss despite robust sales. Spending discipline is central to the equity case.
-
The preliminary offer is expensive against current cash earnings. USD 42 multiplied by 320,945,459 expected post-offering common shares implies USD 13.480 billion of basic equity value. Trailing revenue is USD 1.425 billion, implying 9.46x sales. Trailing FCF, defined here as operating cash flow less purchases of property, equipment and intangible assets, is USD 239.241 million: approximately 56.3x equity value/FCF. These are preliminary, basic-share calculations, excluding additional potential dilution, and are neither a traded share quote nor a final IPO price.
-
The IPO provides liquidity much more than incremental growth capital. Selling shareholders account for 36.5 million of 50.0 million offered shares, or 73%. At the midpoint, estimated issuer net proceeds of USD 532.6 million are largely allocated to USD 526.4 million of employee award tax withholding and remittance. Only about USD 6.2 million remains from those proceeds for general purposes. Strong product adoption therefore cannot be paired with a claim that the headline offering delivers a large new operating cash reserve.
The valuation test is demanding even without a forecast. At unchanged basic equity value, a hypothetical 30x normalized annual earnings multiple requires approximately USD 449 million of profit. At an assumed 15% net margin, that would require approximately USD 3.0 billion of annual revenue, more than twice current trailing revenue. This is a reverse valuation illustration, not management guidance, a target price or an earnings forecast. Continued rapid adoption can support that outcome, but the present operating margin does not yet support assuming it.
The research trigger is the September 21 amended prospectus and September 22 LBank listing. OURA is the proposed Nasdaq ticker in the preliminary filing. This report assesses an IPO-stage company; it does not assume that the US listing has already completed. OURAUSDT is a separate USDT-margined perpetual contract. Its price, funding and liquidation mechanics cannot be substituted for the economics of owning Oura common stock.
2. Company Overview, Business Mix, and Core Operating Metrics
Oura Inc. sells a finger-worn sensor and access to software that interprets personal health data. Oura Health Oy became its subsidiary in the March 2026 reorganization. The business has two linked revenue streams: an upfront hardware purchase and ongoing Oura Membership. Its commercial task is to make measurements useful enough that consumers keep wearing the product and paying for interpretation after the novelty of a new device fades.
Oura Ring: the product behind the investment thesis
Oura Ring addresses a practical constraint in wearables: sustained use, especially overnight. A ring can coexist with a conventional watch and does not require another screen on the wrist. The relevant purchase decision is whether unobtrusive tracking and useful feedback justify both the initial price and a recurring bill. Sleep, recovery and daily habits provide repeated opportunities for engagement, but a score that users stop finding useful also creates a clear cancellation trigger.
Oura Ring 5 was announced on May 28 and launched on June 4, 2026. The manufacturer advertises 40% less volume than Oura Ring 4, dimensions of 6.09 mm by 2.28 mm, and 6–9 days of battery life. The US store lists Silver and Black at USD 399 and premium finishes at USD 499. These are manufacturer specifications and retail prices, not independently tested performance or realized company revenue per ring.
The engineering case connects directly to the business model. Smaller dimensions can reduce discomfort; fewer charging interruptions can improve wearing consistency; better sensor contact can reduce missing data. Our inference is that these improvements may support retention and broaden the buyer base. They must ultimately show up in returns, warranty claims and paid member behavior. A product generation with excellent launch demand but poor long-term reliability would weaken both hardware margins and subscriptions.
The software adds context to sleep, readiness, activity and stress measurements, with Oura Advisor and newer experiences extending the relationship beyond a nightly score. The company says several new software features also support Gen3 and newer rings. That can protect subscription value for existing customers, while reducing the need for every software improvement to force a hardware upgrade. The investment implication is a trade-off between retained subscriptions and replacement hardware revenue.
US Oura Membership costs USD 5.99 monthly or USD 69.99 annually, with an included first month for new members. The subscription attaches to the account rather than each additional ring. Buying another ring is therefore not equivalent to adding another paying member. Oura itself states that its product is not intended to diagnose conditions such as sleep apnea or insomnia. This report assigns no separate valuation premium to unproven medical reimbursement or diagnostic revenue.
|
Business / channel
|
9M FY2026 revenue, USD million
|
Share
|
Economics and customer relationship
|
|
Hardware
|
973.980
|
80.2%
|
Ring purchases through direct, retail and enterprise routes; replacement and acquisition cycles drive demand.
|
|
Membership
|
240.526
|
19.8%
|
Recurring software access; 89% reported gross margin, before shared operating expenses.
|
|
Total
|
1,214.506
|
100.0%
|
An integrated consumer hardware and subscription model.
|
|
DTC channel, included above
|
723.791
|
59.6%
|
Includes direct customer economics; not an additional segment.
|
|
Wholesale channel, included above
|
490.715
|
40.4%
|
Retail and enterprise distribution expands reach; not incremental to the total.
|
Revenue classifications and channel views overlap and must not be added together. The revenue period covers nine months ended June 30, 2026. No standalone operating margin for membership is disclosed here; its gross margin excludes corporate acquisition and development spending.
Core operating metrics and changes
|
Metric / event
|
Latest reading
|
Comparison / implication
|
|
Paid Members
|
5.0 million at June 30, 2026
|
2.5 million a year earlier; management expects approximately 5.7 million at fiscal year-end.
|
|
Rings Sold
|
3.1 million in 9M FY2026
|
1.8 million in the prior period; rounded units should not be used to reverse-engineer exact RPU.
|
|
Revenue per unit (RPU)
|
USD 311 in 9M FY2026
|
USD 326 in FY2025; different-length periods and channel/generation mix.
|
|
Member conversion / retention
|
Over 94% historical conversion; approximately 85% 12-month retention
|
Conversion concerns activations; retention is cohort-weighted and includes defined winbacks.
|
|
Repeat purchases
|
11% of Rings Sold in 9M FY2026
|
9% in FY2025; repeat hardware purchases do not automatically add subscriptions.
|
|
June-quarter performance
|
USD 408.724 million revenue; USD 9.966 million net loss
|
Adjusted EBITDA USD 10.710 million; rapid revenue growth has not insulated quarterly earnings.
|
|
Distribution
|
Approximately 8,400 retail doors
|
Greater reach can increase sell-in ahead of ultimate consumer activation.
|
|
LBank launch
|
September 22, 2026, 06:20 UTC
|
OURAUSDT perpetual; USDT-margined; funding every 8 hours under the launch announcement.
|
Rings Sold is net of returns, warranty replacements and certain exchanges, and excludes deferred-revenue units. Paid Members is a point-in-time subscription metric, whereas membership revenue accumulates over a period. Comparing either to total retail units without those definitions would exaggerate conversion or understate churn.
The September 30 expectation of 5.7 million members is particularly useful because it turns the product narrative into a near-term measurable result. It remains forward-looking as of this report. The disclosed average RPU also shows why the USD 399 retail entry price should not be multiplied mechanically by all units: wholesale terms, promotions and product mix affect recognized revenue.
3. Fundamental Quality
|
Metric, USD million unless stated
|
FY2024
|
FY2025
|
9M FY2025
|
9M FY2026
|
|
Revenue
|
406.751
|
907.856
|
697.569
|
1,214.506
|
|
Gross profit
|
264.094
|
471.012
|
356.025
|
662.167
|
|
GAAP gross margin
|
64.9%
|
51.9%
|
51.0%
|
54.5%
|
|
GAAP operating profit
|
13.440
|
45.332
|
60.265
|
71.188
|
|
GAAP operating margin
|
3.3%
|
5.0%
|
8.6%
|
5.9%
|
|
GAAP net income
|
3.649
|
0.012
|
1.573
|
60.768
|
|
Operating cash flow
|
28.227
|
121.693
|
135.315
|
328.008
|
|
Purchases of property, equipment and intangible assets
|
13.189
|
21.724
|
12.819
|
66.240
|
|
FCF, report definition
|
15.038
|
99.969
|
122.496
|
261.768
|
|
Unrestricted cash at period end
|
105.200
|
764.157
|
Not included
|
371.764
|
|
Debt at period end
|
Not included
|
3.226
|
Not included
|
380.135
|
Fiscal years end September 30; nine-month periods end June 30. Annual statements are audited and interim statements unaudited. FCF is this report’s calculation, not a company-promoted performance measure, and excludes acquisitions. FY2025 cash excludes USD 96.389 million of restricted cash. Historical debt cells marked “Not included” are not zero. Margins are calculated from unrounded amounts rather than the prospectus’s whole-percentage presentation.
Growth quality is strong, but the cost of growth is rising. Revenue increased 74.1% in the comparable nine-month periods while sales and marketing increased 84%, R&D approximately 105%, and general and administrative expense approximately 132%. Gross profit grew rapidly, yet most of the increase was absorbed by operating expenses. The investment question is whether those costs establish capacity for future growth or become a permanently expensive requirement for adding customers.
Profit and cash require separate interpretations. The nine-month USD 60.768 million net profit coexists with a USD 924.255 million loss attributable to common stockholders after a USD 985.023 million deemed preferred dividend. That common-stockholder loss is not an operating loss of the same amount. Equally, removing it does not erase the economic consequences of capital allocation. Pre-IPO EPS and weighted-average shares are poor direct inputs for a post-IPO valuation because the capital structure changes substantially.
Nine-month operating cash flow of USD 328.008 million exceeds net income by a wide margin. Net working-capital changes contributed USD 238.928 million, calculated from the cash-flow statement’s receivables, inventories, prepayments, payables, accruals, deferred revenue and customer deposits. Subtracting those changes and USD 66.240 million of asset purchases leaves USD 22.840 million. This is a deliberately strict cash-conversion diagnostic, not normalized FCF: some advance subscription collections and supplier financing can persist with growth. It demonstrates why the USD 261.768 million reported-period FCF calculation should not simply be annualized.
Hardware quality is a material financial variable. The prospectus attributes a USD 84.4 million increase in FY2025 warranty expense to battery issues in certain Oura Ring 4 cohorts. This figure is an increase, not total warranty expense. Warranty costs rose another USD 28.6 million year over year in the latest nine-month period, even as the relative warranty rate improved. Oura Ring 5’s battery redesign is commercially relevant, but a new product announcement is not proof that future warranty exposure has disappeared.
Liquidity is adequate, with limited net cash protection. June cash of USD 371.764 million was slightly below USD 380.135 million of debt. A USD 25 million revolver repayment in August reduced that facility’s balance to USD 350 million; without a contemporaneous full balance sheet, it should not be combined with June cash to manufacture a current net-cash figure. The filing states that revolving borrowings were used primarily for equity repurchases and general purposes. Alongside the IPO proceeds allocation, this makes governance and capital deployment meaningful parts of the valuation debate.
A reproducible business-to-profitability bridge
Consider a sensitivity of 1.0 million additional average paying members sustained for a full year, priced at the US annual rate of USD 69.99. That yields USD 69.990 million of incremental subscription revenue. Holding the reported 89% membership gross margin constant implies approximately USD 62.291 million of gross profit. If incremental acquisition, support and development expense absorbs an assumed 40% of that gross profit, incremental operating profit is approximately USD 37.375 million. At an assumed 25% tax rate and with no incremental working-capital or capital expenditure requirement, the simplified after-tax cash contribution is approximately USD 28.031 million.
At an illustrative 30x multiple, that cash contribution corresponds to approximately USD 841 million of value, about 6.2% of the indicative basic IPO equity value. This sensitivity is not a sum-of-the-parts appraisal: it omits hardware profit and acquisition hardware requirements, uses US pricing rather than realized global ARPU, and assumes a full-year average member addition. Its purpose is to show how subscription progress must translate into retained profit before it can support a large valuation. One million members added only at year-end would deliver much less current-year revenue.
The single most important variable is therefore contribution after acquisition and servicing per retained member. Member growth without operating-margin expansion would reinforce the cautious valuation assessment; sustained member growth accompanied by lower support intensity and better expense absorption would weaken it.
4. Industry and Competitive Landscape
The relevant market is consumer wearables and paid health insight, spanning rings, watches and screenless bands. A device can complement another wearable, so a hardware sale does not necessarily represent a competitor displaced. Conversely, consumers have limited willingness to pay multiple subscriptions for overlapping sleep and recovery information. The hardest competition may occur at the recurring software bill rather than the initial hardware purchase.
|
Competitive dimension
|
Oura position
|
Rivals / constraint
|
Investment implication
|
|
Wearability
|
Dedicated ring and overnight use case
|
Apple Watch, Garmin wearables, Samsung Galaxy Ring
|
A differentiated form factor can expand demand, but competing products serve overlapping needs.
|
|
Recurring relationship
|
5.0 million Paid Members; approximately 85% 12-month retention
|
Competing ecosystems and devices without a required subscription
|
Pricing depends on the continuing usefulness of interpretation.
|
|
Distribution
|
Approximately 8,400 retail doors
|
Large incumbents have existing devices, channels and customer relationships
|
More doors help acquisition, while channel mix can dilute realized RPU.
|
|
Scale definition
|
Approximately 2% of broad wearable unit market, as presented in the filing using IDC
|
Broad wearable units are not the smart-ring market
|
No unsupported dominant ring-market percentage is assumed.
|
|
Intellectual property
|
Patent licensing agreement with RingConn
|
Licensing also preserves a competing product in the market
|
Potential economic protection; no undisclosed royalty revenue is capitalized.
|
Oura’s cited broad-market share and its ring-category position use different denominators. This report does not derive a precise smart-ring share from overall wearable shipments or from retail visibility.
|
Company / relevant business
|
Period
|
Revenue or operating scale
|
Profit / growth
|
Competitive reading
|
|
Oura Inc.
|
9M ended June 30, 2026
|
USD 1,214.506 million; 5.0 million Paid Members
|
Revenue +74.1%; GAAP operating margin 5.9%
|
Demand winner with unfinished operating leverage.
|
|
Garmin Ltd. — Fitness
|
Quarter ended June 27, 2026
|
USD 756.823 million segment revenue
|
Revenue +25%; USD 277.039 million operating profit, 36.6% margin
|
Profitable winner; CIRQA adds a screenless alternative without a required subscription.
|
|
Apple Inc. — Wearables, Home and Accessories
|
Quarter ended June 27, 2026
|
USD 7,883 million category revenue
|
Growth 6.5%; standalone category operating margin not disclosed
|
Distribution and ecosystem strength; category includes more than Apple Watch.
|
|
Samsung Electronics — MX and Networks
|
Quarter ended June 30, 2026
|
KRW 33.2 trillion combined revenue
|
KRW 0.7 trillion operating loss; calculated margin -2.1%
|
Near-term margin loser in this broad business; not evidence that Galaxy Ring alone loses money.
|
Periods, business scope and currencies differ; these are operating benchmarks, not a uniform valuation peer set. Garmin Fitness includes more than screenless devices; Apple’s category includes home products and accessories; Samsung’s category is dominated by businesses beyond rings. No ring-specific revenue is inferred for either incumbent.
Garmin is the clearest demonstrated profitability competitor. Its Fitness segment combines growth with a far higher operating margin, while CIRQA challenges the proposition that useful continuous wellness feedback must require a separate subscription. Oura can still win users who prefer a ring, but Garmin’s results limit the argument that low operating profitability is an unavoidable feature of all wearable businesses.
Apple retains ecosystem advantages, while Samsung’s broader mobile economics are under pressure. Neither conclusion establishes who is gaining ring share: Apple does not disclose an Oura-comparable subscriber base, and Samsung’s MX and Networks loss reflects a much wider operation. Our competitive inference is that Oura is a net beneficiary of demand for discreet continuous tracking, but must keep funding meaningful differentiation as capable incumbents and licensed ring rivals contest the same customer budget.
RingConn’s announced licensing arrangement illustrates a nuanced moat. Intellectual property can create costs for competitors and potential revenue for Oura, but a license also allows a rival to continue competing. The agreement does not establish perpetual exclusivity or disclose enough financial detail to justify a separate licensing valuation. The durable business advantage must still come from better user experience, retention and profitable acquisition.
5. Key Risks
-
Acquisition becomes less efficient. If Paid Member growth slows while sales and marketing continues growing faster than revenue, the subscription base becomes more costly to replenish. That would compress operating profit even with high membership gross margins.
-
Reliability problems recur. Higher battery failure, replacement or return rates in Oura Ring 5 would raise cost of revenue and servicing expense, while interrupted usage could reduce renewals. The risk reaches both sides of the business model.
-
Recurring pricing meets stronger substitutes. If comparable insight is available within customers’ existing wearable ecosystems or without a required subscription, Oura may need more features, discounts or support to maintain retention. Each response can reduce lifetime contribution.
-
Cash conversion normalizes downward. Rebuilding inventory, paying accrued liabilities or slower advance subscription collections could reverse favorable working-capital contributions. A lower cash earnings base would make the apparent FCF multiple more demanding.
-
IPO terms and dilution change. A higher final price, additional equity awards or different capitalization would raise the earnings hurdle. Selling shareholder supply and lock-up releases could affect market prices independently of ring demand; preliminary terms do not fix the eventual trading outcome.
-
Health claims or data practices damage trust. Any product restriction, material privacy incident or inability to substantiate a marketed function could weaken engagement and raise compliance costs. The base case assumes a consumer wellness business and does not depend on future diagnostic approvals.
-
The perpetual contract diverges from equity fundamentals. Funding, liquidity, index construction and venue rule changes may drive OURAUSDT away from IPO valuation indications. Leverage can force liquidation before a long-term business thesis has time to play out; the launch announcement’s maximum 50x leverage is a contract parameter, not an investment assumption.
6. Monitoring Checklist
The thresholds below are research decision rules, not company guidance except where expressly identified.
-
September 30 Paid Members: compare with management’s approximately 5.7 million expectation. A result below 5.5 million would challenge near-term adoption assumptions; meeting the expectation supports demand but does not alone resolve valuation.
-
Retention and activation: retention materially below 85%, especially below 80% on a comparable cohort definition, would weaken the subscription thesis. Compare conversion with the historically disclosed level above 94% using the same activation definition.
-
Operating leverage: improvement beyond a 10% GAAP operating margin across comparable periods, supported by lower expense growth than revenue growth, would weaken the cautious view. A margin below 5% despite rapid revenue growth would reinforce it.
-
Hardware quality and realized pricing: track warranty expense relative to hardware revenue and cohort age, together with RPU. A further RPU decline without lower unit cost or stronger lifetime subscription contribution would signal deteriorating economics.
-
Cash conversion: reconcile every quarter’s operating cash flow with accruals, customer advances and inventory. FCF sustained without large liability build-up would strengthen quality; a cash reversal would reduce confidence in trailing multiples.
-
IPO completion and capitalization: replace the indicative USD 40–44 range and 320,945,459 basic shares with final pricing, award and prospectus data. Recalculate valuation and dilution, including actual tax settlement and proceeds use.
-
Competitor economics: compare Oura with Garmin Fitness growth and margins, Apple’s relevant category and Samsung’s product developments. Stronger substitutes combined with falling Oura retention would matter more than category growth alone.
-
LBank contract mechanics: monitor the official index, mark price, funding and rule updates, including any IPO transition terms. A contract premium or discount must be analyzed separately from changes in company value.
7. Sources
-
Oura Inc. Form S-1/A — September 21, 2026 (https://www.sec.gov/Archives/edgar/data/2133022/000119312526396051/d119865ds1a.htm) — Primary source: preliminary offering terms, financial statements, operating metrics, capital allocation and risks.
-
Oura Inc. Form S-1 — September 3, 2026 (https://www.sec.gov/Archives/edgar/data/2133022/000119312526381855/d119865ds1.htm) — Primary source: original registration and historical financial statements; the amendment controls offering and share-count assumptions.
-
-
OURAUSDT Futures Trading | LBank Futures (https://www.lbank.com/futures/ourausdt) — User-confirmed official route, retrieved September 23, 2026; static page identifies OURAUSDT. No executable quote or live order book independently verified.
-
-
-
-
Oura Membership (https://support.ouraring.com/hc/en-us/articles/4409086524819-Oura-Membership) — Updated September 8, 2026; subscription pricing, trial and account terms.
-
-
Garmin announces second quarter 2026 results (https://investors.garmin.com/news-and-events/news/news-details/2026/Garmin-announces-second-quarter-2026-results/default.aspx) — July 29, 2026; Fitness segment financials and CIRQA product positioning.
-
-
-
-
-
Data boundaries: Information was checked on September 23, 2026. IPO terms remain preliminary. The report does not provide a final listing date, a live equity quote, analyst consensus or an executable futures quote. The LBank route was supplied and confirmed by the user; its static HTML identifies OURAUSDT and the official announcement verifies the listed contract, but an interactive order book was not independently inspected. Financial amounts are primarily from the SEC filing; current product specifications are manufacturer claims. Basic-share valuation excludes potential incremental dilution and is not a fully diluted market capitalization. All sensitivities and monitoring thresholds are explicitly analyst assumptions.